Your Parent's Medicare Plan Is Ending. Now What?
One real decision families face with an aging parent, answered all the way through.
Your Parent's Medicare Plan Is Ending. Now What?
Stream below or download MP3 for a family meeting or car ride.
Jump to Chapter (Click timestamp to seek audio):
This episode uses AI-generated voices. The script was researched, written, and fact-checked by the families.care team, and the figures in it come from official sources.
Key takeaways
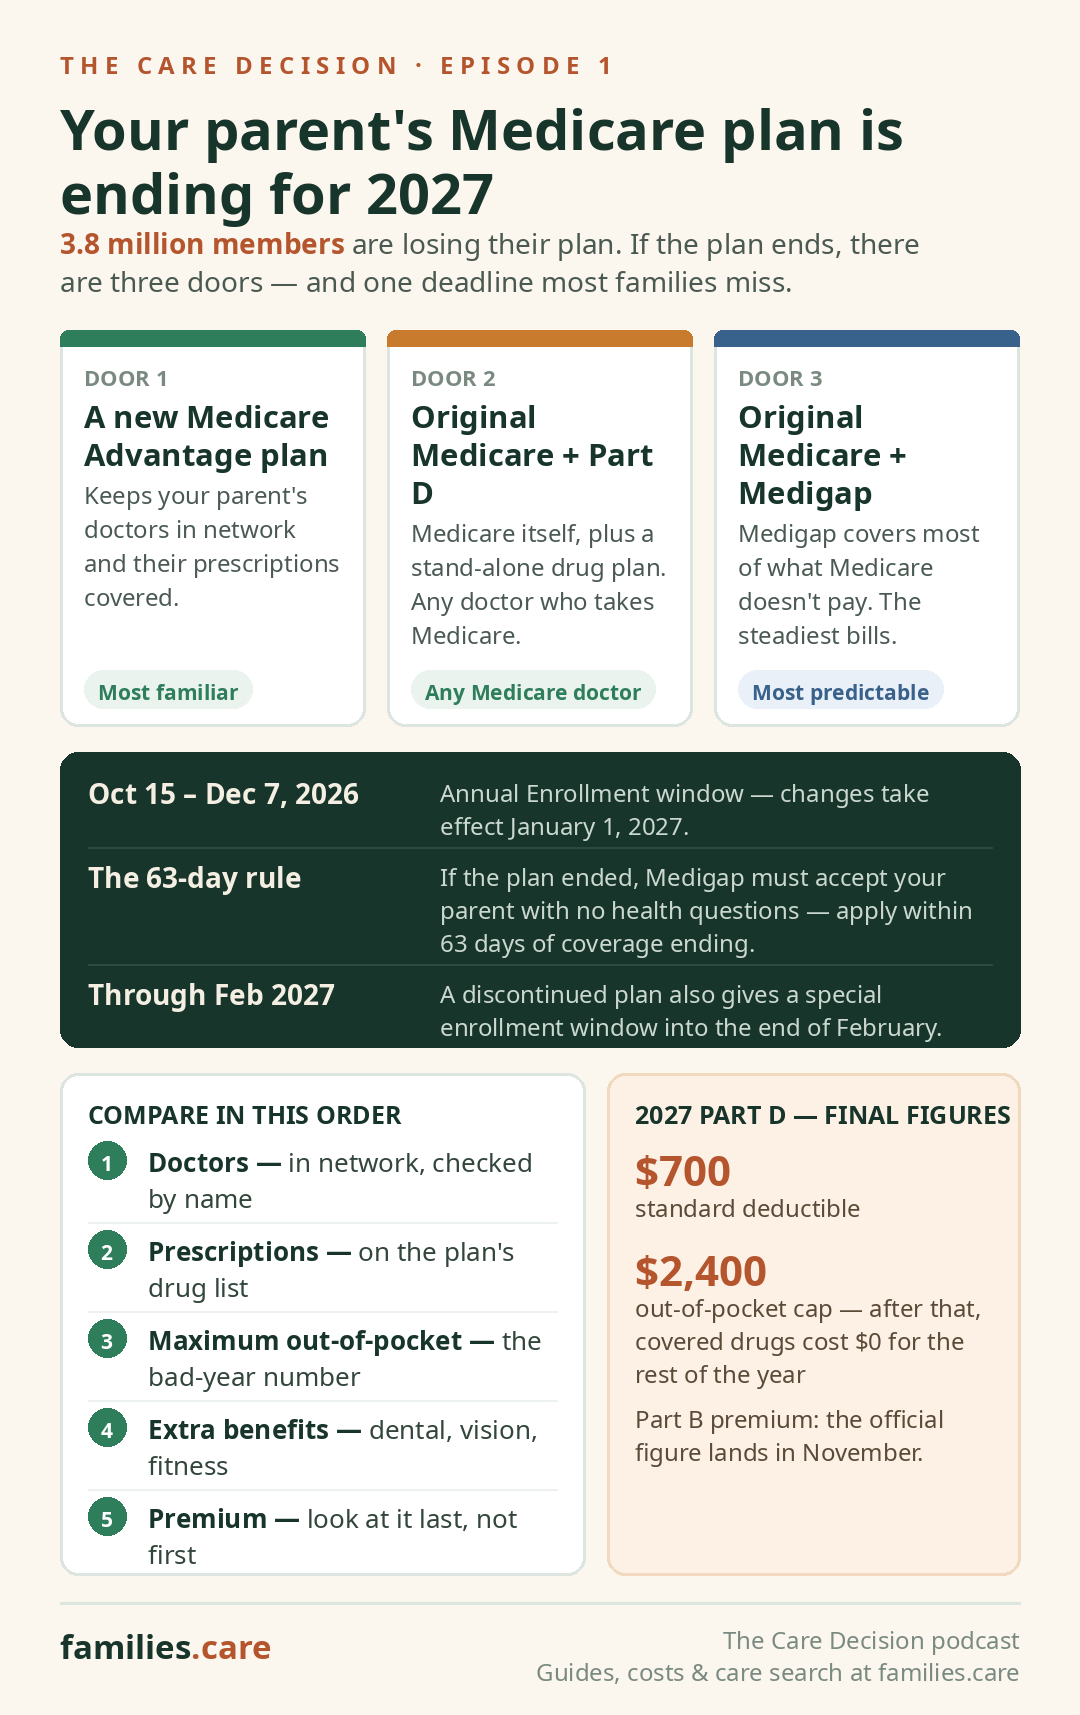
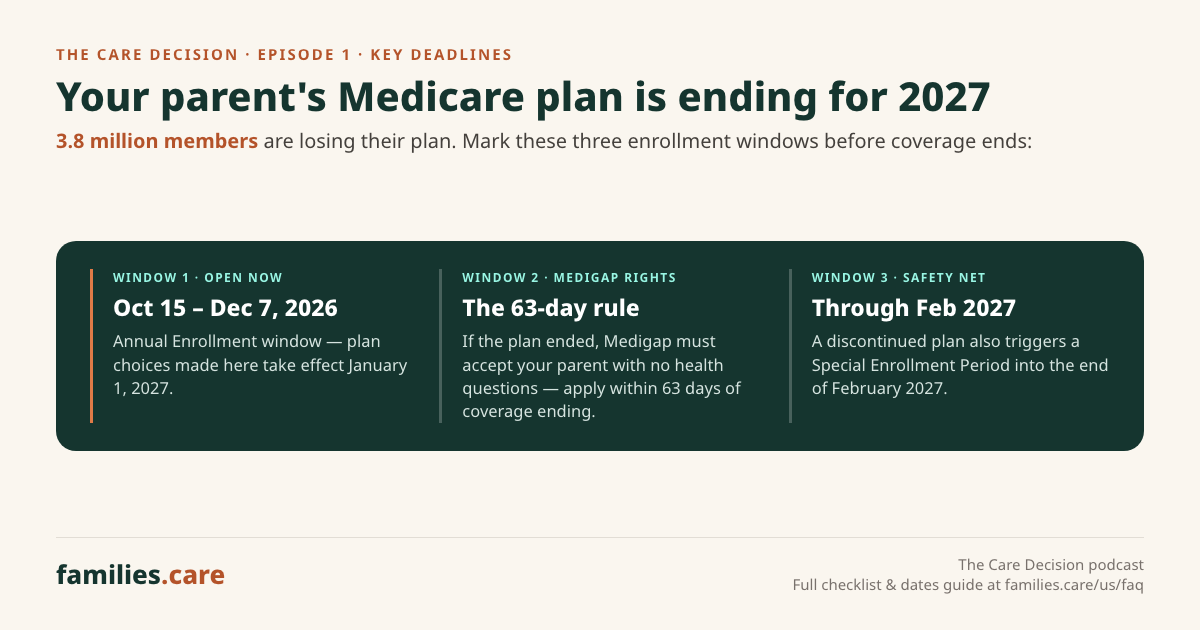
- 01Medicare's annual enrollment window runs October 15 – December 7, 2026; changes take effect January 1, 2027.
- 02If your parent's plan is being discontinued, they also get a special enrollment period through the end of February 2027.
- 03Guaranteed-issue Medigap window: in most cases, apply within 63 days of the old coverage ending or the medical-underwriting questions come back.
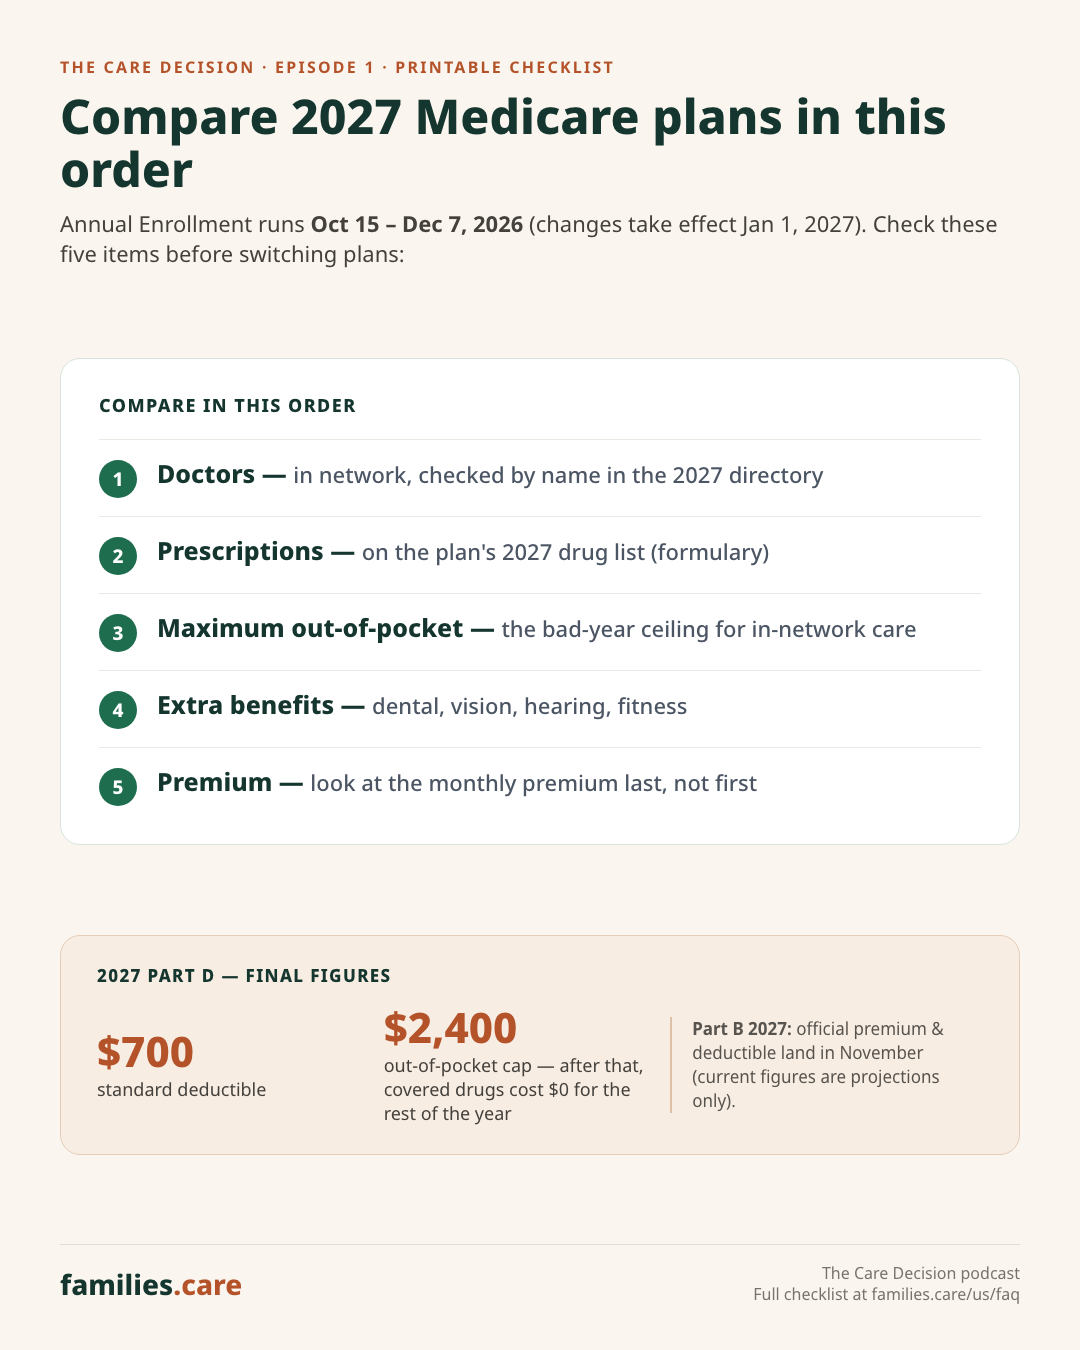
- 04Compare in this order: doctors → prescriptions → maximum out-of-pocket → extra benefits → premium last.
- 052027 Part D (final): $700 standard deductible, $2,400 out-of-pocket cap. 2027 Part B premium: projection only until the official CMS announcement in November.
- 06The 2027 Social Security cost-of-living adjustment is 3.6% — do the household math after the November premium announcement, because the premium comes straight out of the Social Security check.
Printable Reference Cards for Episode 1
Designed for families to use during insurer calls, facility tours, and kitchen-table planning. Tap any reference card to open it full screen.
Show notes
Roughly 3.8 million people on Medicare are losing their current health plan for 2027 — insurers are leaving counties, ending contracts, or not renewing plans. If your parent got a thick letter from their insurance company in September and set it aside, that letter may be telling them their coverage ends December 31.
In this episode, Maya and Daniel walk through exactly what to do:
- How to tell if your parent is affected — find the Annual Notice of Change, or call the number on the back of the insurance card and ask one question.
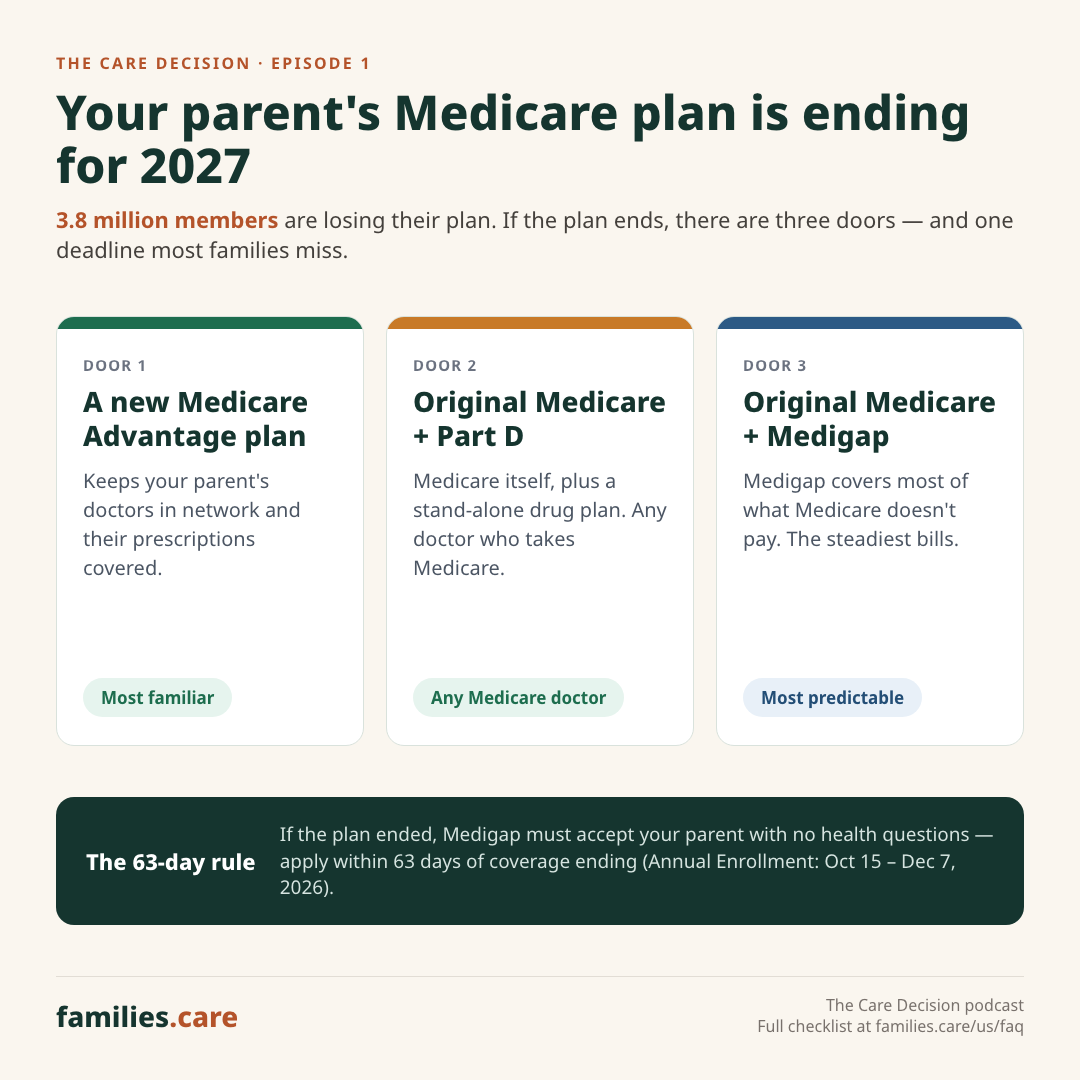
- The three doors — another Medicare Advantage plan; Original Medicare with a stand-alone Part D drug plan; or Original Medicare plus a Medigap supplement.
- The most valuable detail in the episode — when a Medicare Advantage plan ends through no fault of the member, they usually get guaranteed-issue rights to buy certain Medigap policies with no medical underwriting — but in most cases only if they apply within 63 days of the old coverage ending.
- How to compare plans in the right order — doctors in network, prescriptions covered, maximum out-of-pocket, extra benefits — premium last.
- The 2027 figures that are final, and the one that isn't — Part D standard deductible $700 and out-of-pocket cap $2,400 are official; the standard Part B premium is still a projection until CMS announces it in November.
- A five-step checklist to work through before December 7 — and why, for discontinued plans, a special enrollment period through the end of February means December 7 is a deadline worth beating, not a cliff edge.
Guides, costs & care search at families.care.
Links from this episode
Was this episode helpful for your family’s decision?
Anonymous 1–5 star rating · Helps families find the clearest guides first.
Turn This Episode Into Your Local Plan
National averages only tell half the story. Check the exact figures, Medicaid waiver rules, and verified communities in your parent’s state and city.
Cost Calculator
Compare Local Care Costs by State & City
See CareScout 2025 assisted living medians and estimated memory care rates in your area.
Provider Directory
Search Verified Local Communities
Filter assisted living, memory care, and skilled nursing near your parent’s ZIP or city.
State & Federal Guides
Medicare, Medicaid & Care Checklists
Step-by-step written guides grounded in CMS rules and state Medicaid statutes.
Full transcript (the recording script)
This is the production script reproduced verbatim, exactly as recorded.
Maya: A quick note before we begin. This episode uses A I generated voices. The script was researched, written, and fact checked by the families dot care team, and the figures in it come from official sources.
Maya: Welcome to The Care Decision, the families dot care podcast, where we take one real decision that families face with an aging parent, and we answer it all the way through. I am Maya.
Daniel: And I am Daniel. Maya, today the decision is a big one, and it is landing in mailboxes all over the country right now.
Maya: It is. Here is the situation. Roughly three point eight million people on Medicare are losing their current health plan for twenty twenty-seven. Their insurers are leaving counties, ending contracts, or simply not renewing the plans. So if your mom or dad got a thick letter from their insurance company in September, the one most people set aside, that letter may be telling them their coverage ends on December thirty-first.
Daniel: Let me ask the question every family asks first. How do you know if your parent is one of the three point eight million?
Maya: You look for one specific document. It is called the Annual Notice of Change, and plans were required to send it in the fall. If the plan is ending entirely, the letter says so plainly, usually in the first page or two. If you cannot find the letter, that is fine. Log into your parent's account on their insurer's website, or call the number on the back of their insurance card, and ask one question: will this exact plan exist in my parent's county in twenty twenty-seven?
Daniel: And the timing matters here, because Medicare's annual enrollment window opens tomorrow, October fifteenth, and it runs through December seventh. Any change your parent makes in that window takes effect on January first, twenty twenty-seven.
Maya: That is the main window, and for most families it is the one to use. But here is the part that calms people down. If your parent's plan is being discontinued, they also get a special enrollment period that runs through the end of February. So December seventh is not a cliff edge for them. It is a deadline worth beating, because coverage choices are widest early, but it is not the last day to act.
Daniel: Okay, so the plan is ending. What are the actual choices?
Maya: There are really three doors. Door one is another Medicare Advantage plan, ideally one that keeps your parent's doctors in network and their prescriptions covered. Door two is going back to Original Medicare, usually paired with a stand-alone Part D drug plan. And door three is Original Medicare plus a Medigap supplement policy, which is the combination that gives the most predictable costs, because Medigap picks up most of what Medicare does not pay.
Daniel: Door three is normally the hard one, because Medigap usually involves health underwriting. The insurer can ask medical questions and can say no.
Maya: Normally, yes. But this is the single most valuable detail in today's episode. When a Medicare Advantage plan ends through no fault of the member, that person usually gets what is called guaranteed issue rights. That means they can buy certain Medigap policies without medical underwriting, with no health questions deciding the answer. There is a clock on it, though. In most cases you apply within sixty-three days of the old coverage ending. Miss that window, and the underwriting questions come back.
Daniel: So the sequence matters. You do not just pick the cheapest premium and move on.
Maya: Exactly. And that brings us to the mistake we see families make every year. They compare premiums. Just premiums. But the number that actually hurts families is the maximum out of pocket, the most the plan can make you pay in a bad year. Two plans can both cost zero dollars a month in premium, and one can cap your yearly exposure thousands of dollars lower than the other.
Daniel: What else belongs on the comparison list?
Maya: Four things, in this order. First, are your parent's actual doctors and hospital in the network, checked by name, not by a brochure. Second, are their exact prescriptions on the plan's drug list, at a tier they can afford. Third, that maximum out-of-pocket number. And fourth, the extra benefits they quietly rely on, like dental, vision, or a fitness benefit, because those often vanish in the new plan and families only notice in March.
Daniel: Let me ground this in the money for twenty twenty-seven, because some of those numbers are now official. What do we know for sure?
Maya: For the Part D drug benefit, the twenty twenty-seven figures are final. The standard deductible is seven hundred dollars, and the out-of-pocket cap, the most anyone pays for covered prescriptions in a year, is two thousand four hundred dollars. Once your parent spends past that cap, their covered drugs cost them nothing more for the rest of the year. What is not final yet is the standard Part B premium. The official announcement comes in November, so treat any number you see for it today as a projection, including ours.
Daniel: And one more piece of good news on the income side. The Social Security cost-of-living adjustment for twenty twenty-seven was announced this morning at three point six percent, which works out to roughly seventy-five dollars a month on the average benefit. That raise helps, but it also means families should do this math after the November premium announcement, not before, because the premium is deducted straight from the Social Security check.
Maya: Which is a perfect summary of the season we are in. So let me give you the checklist we would hand our own families. Step one, find the letter, or call the insurer and confirm whether the plan exists next year. Step two, write down your parent's doctors and their full prescription list, because every comparison runs on those two lists. Step three, compare plans on medicare dot gov with those lists in hand, and check the maximum out of pocket before you look at premiums. Step four, if Medigap might be the right door, protect the guaranteed issue window, and do not let those sixty-three days drift. And step five, make the change before December seventh if you can, so January starts clean.
Daniel: And if a family is walking through this while also comparing care facilities, or trying to work out what care itself will cost next year, that is the other half of what we do. The written version of today's checklist, and our guide to funding care, are both up at families dot care.
Maya: That is our first episode. The Care Decision is about one decision, answered properly, every time. Next time, we take on the question underneath almost every other one: what does memory care actually cost, and what exactly moves that price up or down? I am Maya.
Daniel: And I am Daniel. Thanks for listening, and check on that letter.