
Understanding Medicare and Medicaid for Senior Care: A Family's Complete Guide
Medically Reviewed by Aisha Patel, Registered Nurse
Updated on September 15, 2026
Resource & Funding Hub
Grounded against 5 primary statutory & directory sources.Markdown / Cite ↗
Key Takeaways
Navigate Medicare and Medicaid benefits for senior care, including coverage differences, eligibility, and how to access home care and nursing homes.
Understanding the Basics: Medicare vs. Medicaid
When families begin researching care options for aging loved ones, Medicare and Medicaid are often mentioned as potential funding sources.[1] However, these two government programs serve different purposes and have distinct eligibility requirements, coverage rules, and application processes.
Medicare is a federal health insurance program primarily for people 65 and older, regardless of income level. Think of it as health insurance that you've earned through years of paying into the system through payroll taxes.
Medicaid is a joint federal-state program that provides healthcare coverage for individuals with limited income and assets. For seniors, Medicaid becomes particularly important when Medicare doesn't cover long-term care services.[2]
Medicare Coverage for Senior Care
What Medicare Covers
Medicare consists of several parts, each covering different aspects of healthcare:
- Medicare Part A (Hospital Insurance): Covers inpatient hospital stays, skilled nursing facility care (limited), hospice care, and some home health services
- Medicare Part B (Medical Insurance): Covers doctor visits, outpatient care, medical supplies, and preventive services
- Medicare Part C (Medicare Advantage): Private insurance plans that combine Parts A and B, often including prescription drug coverage
- Medicare Part D: Prescription drug coverage
Medicare's Limited Long-Term Care Coverage
One of the most important things families need to understand is that Medicare provides very limited coverage for long-term care. Here's what Medicare does and doesn't cover:
Medicare DOES cover:
- Skilled nursing facility care for up to 100 days per benefit period (with conditions)
- Home health services if you're homebound and need skilled care
- Hospice care for terminally ill patients
- Durable medical equipment like wheelchairs and hospital beds
Medicare DOES NOT cover:
- Custodial care (help with daily activities like bathing, dressing, eating)
- Long-term nursing home stays
- Most assisted living facility costs
- Adult day care services
Understanding the "Skilled Care" Requirement
For Medicare to cover nursing facility or home health services, the care must be considered "skilled." This means:
- Services must be provided by or under the supervision of licensed professionals
- Care must require medical or nursing expertise
- The person must be making progress or the skilled service must be necessary to maintain their condition
Personal care services like help with bathing, dressing, or meal preparation don't qualify as skilled care under Medicare rules.
Medicaid Coverage for Senior Care
Medicaid's Comprehensive Long-Term Care Coverage
Unlike Medicare, Medicaid is specifically designed to help people with limited resources access necessary healthcare, including long-term care services. For seniors, Medicaid covers:
- Nursing home care
- Home and community-based services (HCBS)
- Personal care services
- Adult day health programs
- Assisted living (in some states)
- Respite care for family caregivers
Medicaid Eligibility Requirements
Medicaid eligibility is based on income and assets, and rules vary significantly by state. Generally:
- Income limits are tied to the Federal Poverty Level (often 100-138% FPL for older adults)
- Asset limits are typically $2,000 for an individual, though some assets like a primary home are exempt up to a certain equity value
- There is a "look-back period" (usually 5 years) during which large asset transfers can trigger a penalty period of ineligibility
- A healthy spouse can keep certain assets and income under "spousal impoverishment" protections
- For long-term care specifically, most states also require a separate functional (level-of-care) assessment — meeting the income limit alone is not enough
2026 Medicare Open Enrollment (Oct 15 – Dec 7) & the 4 Senior Care Funding Bridges
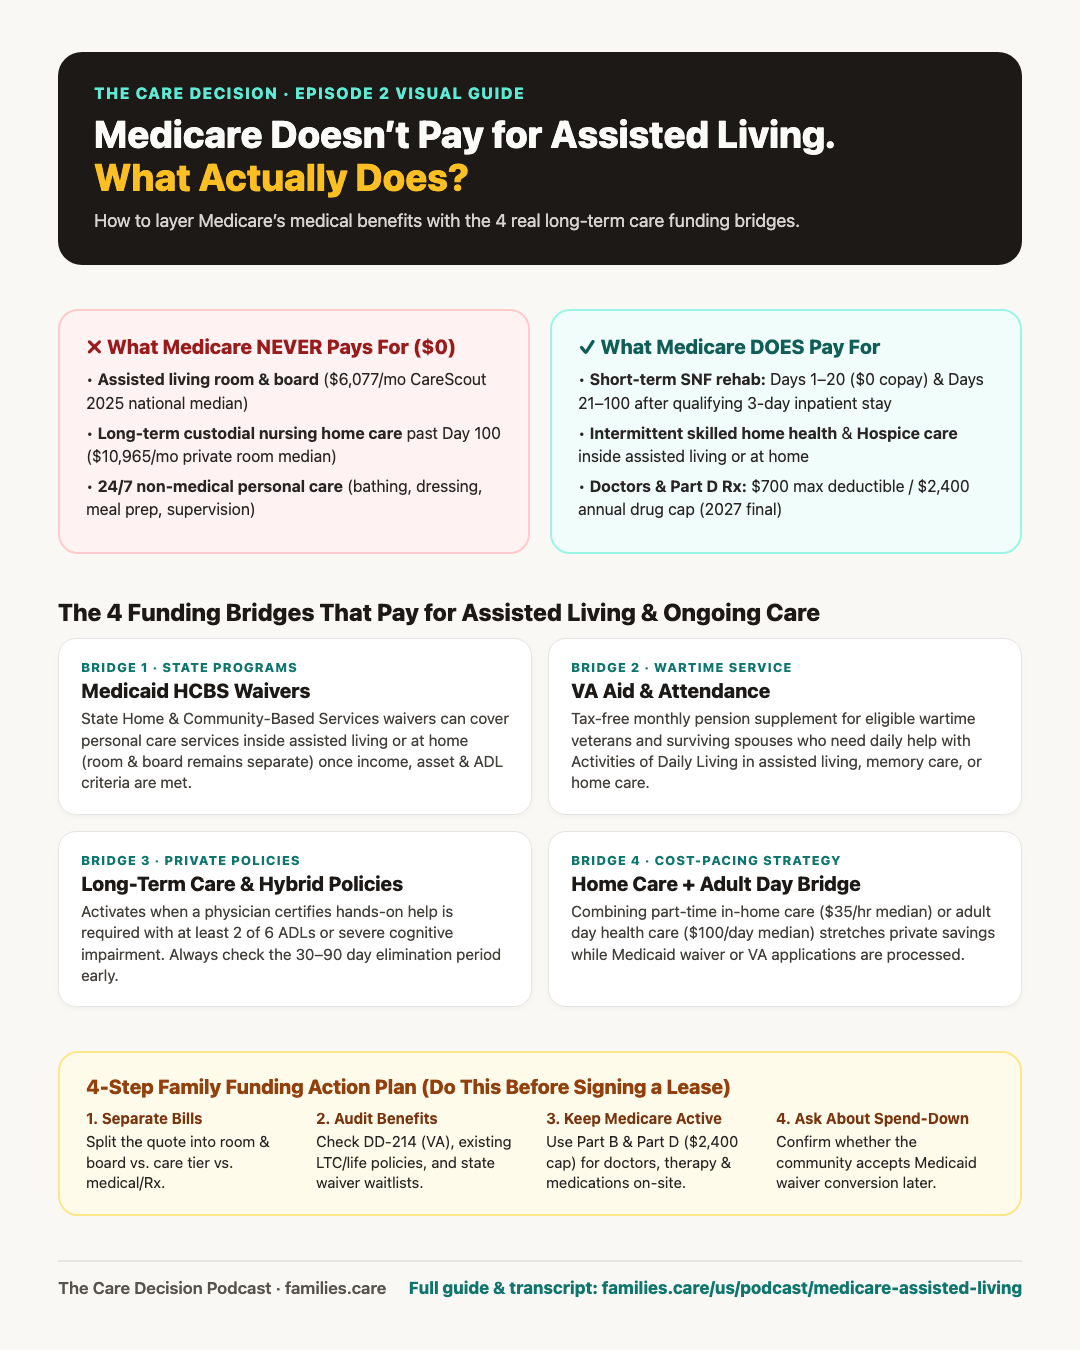
If your family is reviewing coverage during Medicare Open Enrollment (October 15 – December 7, 2026) for plan changes taking effect January 1, 2027 — or planning how to pay for assisted living ($6,077/month CareScout 2025 national median) and long-term care that Medicare does not cover — use these companion guides and visual checklists:
- Medicare Open Enrollment 2026: Key Dates & Plan-Ending Checklist — Oct 15–Dec 7 deadlines, the Feb 28, 2027 non-renewal Special Enrollment Period, the 63-day Medigap guaranteed-issue rule, and the 5-step comparison checklist.
- 2027 Medicare Costs: What Is Final and What Is Still Pending — Finalized 2027 Part D figures ($700 max deductible, $2,400 annual out-of-pocket cap, $41.33/mo base beneficiary premium) and 2026 Trustees Report Part B projections (~$209.50/mo premium and ~$292 deductible, projections only until CMS confirms in November).
- What Medicare Covers (and Doesn’t Cover) for Senior Care — Skilled nursing rehab (up to 100 days), intermittent home health, hospice, and why custodial assisted living room & board is $0 under Medicare.
- The Care Decision Ep 1: Your Parent’s Medicare Plan Is Ending for 2027. Now What? — Full visual pack and 5-segment transcript.
- The Care Decision Ep 2: Medicare Doesn’t Pay for Assisted Living. Here’s What Actually Does — The 4 funding bridges (Medicaid HCBS waivers, VA Aid & Attendance, LTC/hybrid policies, and home-care/adult-day pacing) + full transcript.
- The Care Decision Ep 3: How Families Actually Pay the $6,077/Month Assisted Living Gap — The 3-bucket invoice split, VA Unreimbursed Medical Expense (UME) deductions, LTC 2-of-6 ADL triggers, and 90-day bridge pacing.
Open Enrollment Is Live: Part D Costs Rise to a $700 Deductible and $2,400 Cap in 2027 — But 15 Drugs Get Negotiated Prices
The window and the deadline: Medicare Open Enrollment is open nationwide from October 15 through December 7, 2026, with coverage effective January 1, 2027. For more than 70 million enrolled beneficiaries (including approximately 47.4% projected by CMS in Medicare Advantage for 2027), doing nothing means your current coverage rolls over into its new 2027 price structure automatically — and 2027 is the year "set-and-forget" gets expensive.
| 2027 Parameter | 2026 Benchmark | 2027 Final CMS Level | Annual Change |
|---|---|---|---|
| Standard Part D Deductible | $615 | $700 | +13.8% (largest in Part D history) |
| Out-of-Pocket Prescription Cap | $2,100 | $2,400 | +$300 (+14.3%) |
| Base Beneficiary Premium | — | $41.33/mo | Statutory base rate |
| Social Security COLA | +2.5% | +3.6% | ~$75/mo for average beneficiary |
Why headline averages mislead: The temporary federal Part D Premium Stabilization Demonstration (2025–2026) ends after 2026. While CMS projections show modest movement on average — projecting the average Medicare Advantage premium falling from $14.37 to $12 per month and average standalone Part D premiums increasing by less than $1 per month — individual plan premiums are swinging sharply. Regional reports show wide divergence: one popular Boston AARP/UnitedHealthcare PPO premium jumps +56%, while California’s median standalone Part D premium is reported up +41%. As plans re-price under the Inflation Reduction Act’s benefit restructuring, relying on national averages can conceal severe plan-level cost spikes.
The offsetting good news: On January 1, 2027, the first cycle of Medicare-negotiated drug prices takes effect for 15 widely used prescription drugs, including diabetes and weight-management therapy Ozempic, yielding substantial out-of-pocket relief for enrollees taking those specific therapies. In addition, insulin products remain capped at $35 per month and are exempt from the Part D deductible.
The 5-step caregiver check before December 7:
- Read the Annual Notice of Change (ANOC): Review Section 1 to confirm whether your parent’s current plan is continuing, its 2027 premium, and deductible adjustments. (If their plan is terminating, read our Medicare Advantage plan exits guide for guaranteed-issue Medigap rights).
- Run exact prescriptions through the Medicare Plan Finder: Use Medicare.gov to evaluate total annual cost (premiums plus deductibles plus tier-specific copays), not the headline monthly premium alone.
- Confirm doctors and pharmacy network status: Check that primary physicians and specialists remain in-network for 2027, and confirm whether your filling pharmacy is categorized as a "preferred in-network" pharmacy.
- Consider the Medicare Prescription Payment Plan: Spreads required Part D out-of-pocket costs into capped monthly installments across the year (note: this is a monthly budgeting tool only — it does not reduce total costs).
- Get free, unbiased guidance: Contact your local State Health Insurance Assistance Program (SHIP) for free, one-on-one counseling without sales commissions.
Sources: Centers for Medicare & Medicaid Services (CMS) 2027 Part D parameters; Lone Star 92.5: Medicare Open Enrollment Begins, 2027 Plan Changes Announced (2026-10-15); Consumers’ Checkbook: Medicare Options and Advice (updated 2026-10-16); Money Digest: Retirees Face Historic Medicare Part D Deductible Hike in 2027 (2026-10).
32 Million Americans Are Financial Caregivers — and They’re Spending $8,737 a Year of Their Own Money to Do It
The hidden scale of financial caregiving: A landmark national study by Edward Jones, Age Wave, and The Harris Poll (The Financial Impact of Caregiving, surveying 3,000+ adult caregivers, October 2026) reveals that financial caregiving is a distinct, largely invisible responsibility. 81% of family caregivers for an adult 65+ perform financial caregiving, representing over 32 million American adults. Among them, 91% spend their own money on the care recipient, and 84% are not fully reimbursed — absorbing an average unreimbursed out-of-pocket spend of $8,737 per year, adding up to an aggregate transfer of approximately $235 billion annually. In addition, caregivers provide an average of 109 hours of care per month (~3.6 hours per day).
What financial caregiving means in practice: Beyond direct cash assistance, the role involves balancing checkbooks, managing online accounts, paying bills, filing medical insurance claims, tracking taxes, and coordinating benefits. Yet only 57% of those actively doing this work identify it as "financial support" — seeing it instead as routine family assistance until their personal finances begin to erode.
The planning gap and downstream risk: Only 33% of financial caregivers say the role was planned or discussed in advance, and only 22% felt extremely prepared. Caregivers commonly pull funds from personal emergency reserves, retirement savings, or money earmarked for their children’s education. 8 in 10 caregivers state they would sacrifice their own financial security for the person in their care. As highlighted by McKnight’s Senior Living, this self-sacrifice creates compounding vulnerability: spending down one’s own retirement to support an aging parent can put the caregiver’s own future senior living out of reach (with CareScout’s 2025 national median cost for assisted living at $74,400 per year, or $6,200 monthly).
Two critical cost multipliers:
- Insufficient recipient resources: When the care recipient lacks sufficient retirement savings or pension income, the caregiver’s net annual out-of-pocket contributions climb to an average of $12,863 per year.
- History of financial scams or fraud: When the older adult has been targeted by financial fraud or predatory schemes, caregiver contributions average $10,583 per year to repair credit, restore lost assets, or cover housing.
The 4-step financial caregiving starter checklist:
- Audit accounts and recurring liabilities: Build a complete balance sheet of the care recipient’s monthly income (Social Security, pensions), bank accounts, credit cards, recurring subscriptions, and outstanding debts.
- Execute essential legal authorities: Ensure a durable financial Power of Attorney (POA) and healthcare proxy are in place while the older adult has full legal capacity.
- Establish a written family reimbursement agreement: Draft a clear written agreement between siblings and relatives defining who pays what and how reimbursements occur — essential for preserving family harmony and avoiding Medicaid look-back transfer penalties.
- Implement elder fraud safeguards: Add trusted-contact alerts on brokerage and bank accounts, monitor credit reports, place credit freezes if appropriate, and set daily debit withdrawal limits.
Sources: Edward Jones / Age Wave / The Harris Poll: The Financial Impact of Caregiving (survey of 3,000+ caregivers, Oct 14, 2026); McKnight’s Senior Living: Financial Sacrifices May Put Senior Living Out of Reach for Many Family Caregivers (2026-10-16); CareScout 2025 Cost of Care Survey.
Related Articles
Verified references & primary sources
5 verified sourcesQuantitative and regulatory claims in this guide are grounded against official registries and benchmark datasets.
-
Statutory RegistryCareScout · Verified 2026-08-15 · General senior-care planning information.
-
Statutory RegistryMedicare.gov · Verified 2026-08-15 · General senior-care planning information.
-
Statutory RegistryMedicaid.gov · Verified 2026-07-10 · General senior-care planning information.
-
Statutory RegistryNational Institute on Aging · Verified 2026-07-10 · General senior-care planning information.
-
Statutory RegistryU.S. Department of Veterans Affairs · Verified 2026-08-15 · General senior-care planning information.
How we research and verify this information
Our team compiles this listing from public records and provider data, and reviews it against authoritative sources. Read our editorial standards and research methodology.
- Cost of Care Survey (2025)Publisher: CareScout. Supports: Background information for this senior-care resource guide. Last checked: 2026-08-15.
- Skilled nursing facility coveragePublisher: Medicare.gov. Supports: Background information for this senior-care resource guide. Last checked: 2026-08-15.
- Medicaid coverage and eligibilityPublisher: Medicaid.gov. Supports: Background information for this senior-care resource guide. Last checked: 2026-07-10.
- Long-term-care guidance for familiesPublisher: National Institute on Aging. Supports: Background information for this senior-care resource guide. Last checked: 2026-07-10.
- VA pension rates (Aid & Attendance)Publisher: U.S. Department of Veterans Affairs. Supports: Background information for this senior-care resource guide. Last checked: 2026-08-15.